HOUSING MARKET EVIDENCE BEFORE ASSUMPTIONS
Understanding the residential market before investing.
A strong investment proposition requires a clear view of demand, actual prices, liquidity, competition and legal development capacity. One city-wide average cannot describe every district or project.
01 / OFFICIAL MARKET MOVEMENTS
Agadir apartment transactions recovered in Q2 2026 while prices moved modestly.
The figures below are quarter-on-quarter changes for Agadir city, from the Bank Al-Maghrib and ANCFCC real-estate price index.
APARTMENT PRICE INDEX+0.9%
Q2 2026 vs Q1 2026
APARTMENT TRANSACTION VOLUME+32.3%
Q2 2026 vs Q1 2026
ALL PROPERTY · PRICE INDEX−0.1%
Q2 2026 vs Q1 2026
ALL PROPERTY · TRANSACTIONS+30.1%
Q2 2026 vs Q1 2026
Official source: ANCFCC, Indice des Prix des Actifs Immobiliers — 2nd quarter 2026 ↗. These are percentage changes, not returns earned by an individual investor. The market can differ by district, property type and time period.
02 / DISTRICT ASKING PRICES
Prices vary substantially across Agadir's apartment neighbourhoods.
The table uses median advertised apartment prices collected by FeenWay, updated 7 November 2026. It is a snapshot of asking prices, not completed sales or a formal valuation.
| Neighbourhood | Median advertised apartment price | Number of sale listings |
|---|---|---|
| Hay Mohammadi | 12,500 MAD / m² | 305 |
| Hay Salam | 11,100 MAD / m² | 150 |
| Haut Anza | 10,400 MAD / m² | 86 |
| Hay Houda | 12,300 MAD / m² | 86 |
| Founty | 21,600 MAD / m² | 58 |
| Haut Founty | 17,100 MAD / m² | 54 |
| Anza | 14,400 MAD / m² | 40 |
| Cité Adrar | 10,300 MAD / m² | 36 |
| Tilila | 11,100 MAD / m² | 35 |
Source: FeenWay, Agadir apartment advertisements, data as of 7 November 2026 ↗. Listing medians depend on property mix, condition, advertised floor area and duplicate removal. Values may change and are not evidence that a particular dwelling will sell at that price.
Why a median is not a valuation
Comparisons should adjust for street, building age, permitted use, legal title, floor, finish and access. A few lower-quality listings can change an area's advertised median without changing the economics of a well-specified project.
Why movement is not profit
A price-index increase does not include purchase costs, taxes, financing, construction, maintenance, management, vacancy or the time required to sell. Feasible projects must still work under conservative scenarios.
03 / THE FUNDAMENTALS
Five forces that matter to housing investment.
These are market questions, not forecasts of how many units will be built.
01
Household affordability
Mortgage access, incomes and purchase budgets determine who can buy the finished product.
02
Suitable housing stock
Existing vacancies, seasonal residences and housing quality must be considered before assuming new construction demand.
03
Infrastructure & access
Operational roads, transit, water and services affect residential usefulness and delivery timelines.
04
Employment & services
Stable jobs, schools, health care and daily amenities influence long-term residential demand.
05
Permitted supply
A planning area is not automatically buildable housing land; actual rights, finance and serviced plots must be checked.
04 / READING THE CITY
Growth is not evenly distributed.
Coastal and centrally located neighbourhoods serve different residents and budgets from eastern family districts. New infrastructure can improve access, but zoning, competing supply and the actual ability to pay remain critical.
Agadir Living uses public statistics as a starting point, then asks whether a particular opportunity has verifiable local demand and realistic economics.
Explore neighbourhood considerations ↗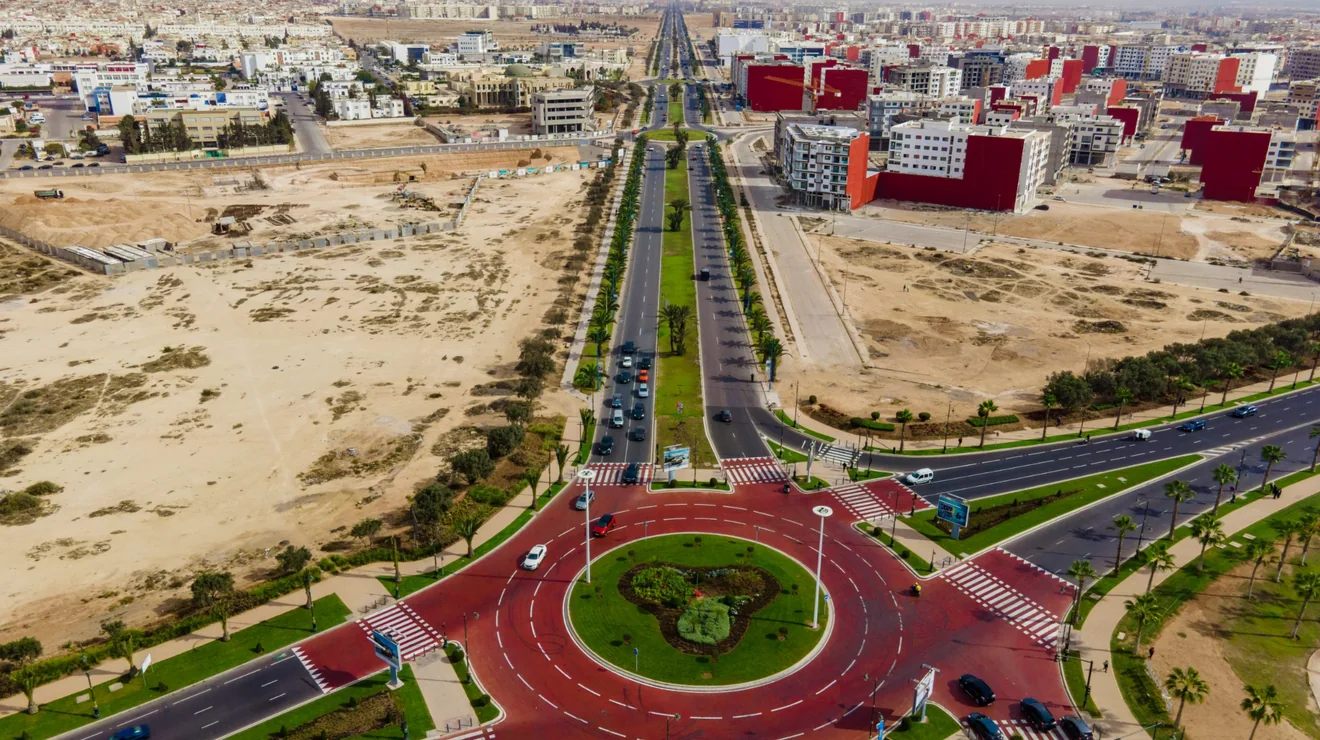
05 / SOURCES & LIMITATIONS
What we publish — and what we do not claim.
Public information is reviewed by source, date and geographic boundary. Internal studies and private investor scenarios are not downloadable through this website.
We deliberately do not display a single “Greater Agadir population” number or a speculative housing-unit target. The municipality, prefecture, wider metropolitan area and Temsia plan cover different geographies.
06 / THE NEXT STEP
A market can be promising without every project being attractive.
Agadir Living examines investment participation against the requirements of the individual investor and the available evidence.
Discuss investment possibilities ↗