
AGADIR INVESTMENT PRESENTATION
The demand base
Agadir is already absorbing substantial population growth.
The 2024 population census records 721,431 residents in Agadir Ida Outanane Prefecture, compared with approximately 600,599 in 2014. That is an increase of about 120,800 people in ten years. The prefecture is now approximately 87% urban.
At the same time, average household size has fallen to about 3.6 people. Population growth combined with smaller households generally means that dwelling formation can grow faster than population alone suggests.
HCP records 143,752 households in 2014 and 197,248 in 2024. Household growth therefore materially outpaced population growth over the decade.
01
The 76,585 figure — correctly framed
TEMSIA IS A MAJOR HOUSING-GROWTH SIGNAL.
The Agadir Urban Agency states that the Temsia communal development plan covers approximately 62 km² and can accommodate a future population of 76,585 by 2035. This does not mean “76,585 additional residents in Agadir city.” It is a planning capacity for the Temsia growth area within Greater Agadir. For investors, it still demonstrates the scale of planned eastward urbanisation.
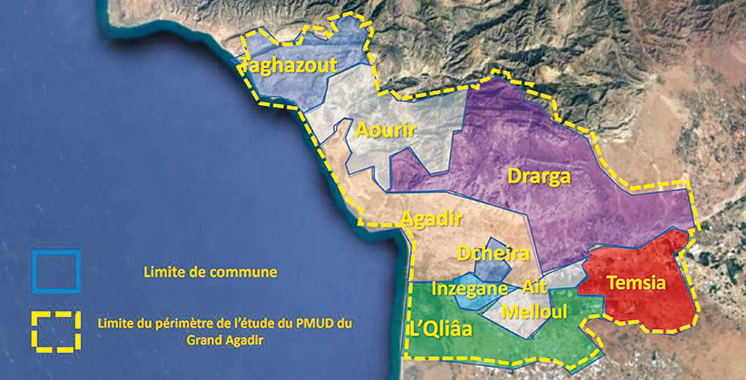
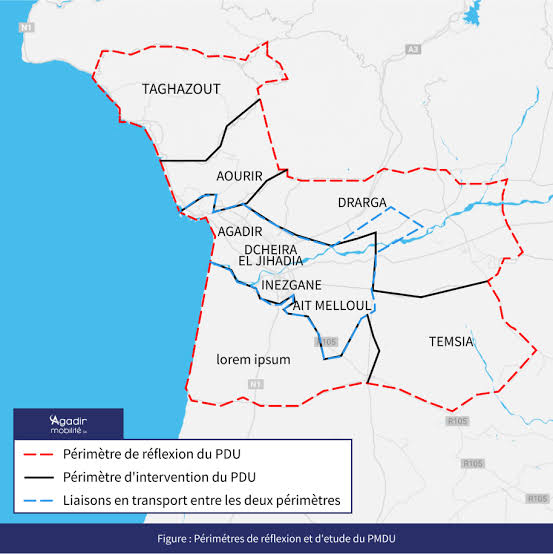
Where housing can expand
SIX CORRIDORS TO WATCH
Planning status matters. The opportunity is strongest where legal development capacity, road access, employment and amenities advance together.
NEW URBAN POLE
1,176 haApproved plan. Health, sport, education and future mobility create an institutional anchor for mixed housing and services.
AGADIR SOUTH
2,458 haLarge sector plan, homologated in 2026. Long-run potential for housing, services and new urban infrastructure.
HAY MOHAMMADI
815 haAn established eastward growth district with approved planning, existing housing and continued commercial and service expansion.
TIKIOUINE
~1,462 haDraft 2026 plan with stronger Drarga–Dcheira road links, public facilities and green space.
TEMSIA / DRARGA
76,585Future population capacity by 2035 in the Temsia plan; strategically connected to eastern employment zones.
ANZA / NORTH
Coastal growthNorthward development combines established neighbourhoods, the port, coastal renewal and access toward the Taghazout corridor.
02
The housing mix is changing
APARTMENTS ARE TAKING A LARGER SHARE OF THE MARKET.
HCP housing data for Agadir Ida Outanane show that 25.1% of urban households lived in apartments in 2024. In urban areas, 29.2% of households are renters. This creates distinct markets for owner-occupier apartments, long-term rentals and carefully selected furnished or tourism-linked units.
Demand segmentation
NOT ONE HOUSING MARKET — FOUR.
Public infrastructure creates opportunity, but the investor still needs to match the product to the end user. A luxury beachfront apartment and an affordable unit near an employment corridor are exposed to different demand drivers.
LOCAL OWNER-OCCUPIERS
Permanent households prioritising access to work, schools, services and financing affordability.
LONG-TERM RENTERS
Urban employees, professionals, students and households that are not yet buying.
MOROCCANS ABROAD
Second-home and family-use demand, supported nationally by a large share of housing-aid beneficiaries living abroad.
VISITOR / SEASONAL DEMAND
Tourism-oriented units in locations where regulation, building rules and management make short-stay use viable.
Affordability & supply
PUBLIC POLICY IS ALSO STIMULATING HOME PURCHASE.
Morocco’s direct housing-aid programme provides support for eligible primary-home purchases, including subsidies of MAD 100,000 for qualifying homes priced up to MAD 300,000 and MAD 70,000 for qualifying homes in the MAD 300,000–700,000 band. In Agadir, Al Omrane has marketed housing such as the Igoudar programme as eligible for direct aid.
This matters for development because demand is not concentrated only at the premium end. Affordable and mid-market housing can be supported by demographics, household formation and policy at the same time.
Latest market pulse · Q2 2026
AGADIR IS ACTIVE — BUT NOT IN A CITY-WIDE PRICE BOOM.
The Bank Al-Maghrib / ANCFCC real-estate price index for the second quarter of 2026 shows why selective buying matters. Agadir’s overall index was approximately 0.1% lower quarter-on-quarter, while apartment prices were reported 0.9% higher and the number of transactions across the city increased by about 30.1% from the previous quarter.
Nationally, residential prices increased by 1.0% year-on-year in Q2 2026. The message is not that Agadir property automatically appreciates; it is that location and asset type can behave very differently inside the same growth story.
03
Property value
INFRASTRUCTURE CAN CREATE VALUE — BUT IT DOES NOT CREATE A GUARANTEED RETURN.
The most useful investor question is not “Will Agadir prices rise?” but “Which locations gain measurable advantages from the city’s growth?” Recent official real-estate price data show only modest national movement and periods of near-flat pricing in Agadir. That makes micro-location, purchase price and product selection more important than a city-wide appreciation assumption.
ACCESS
New roads, Trambus and airport capacity enlarge catchment areas.
AMENITY
Parks, culture, public realm, healthcare and education improve residential utility.
EMPLOYMENT
Industrial, logistics, health, education, tourism and technology activity support permanent demand.
PLANNING
Approved sector plans reduce uncertainty over where urbanisation can legally occur.
SCARCITY
The strongest value effect occurs where improved demand meets constrained or differentiated supply.
Scenario model
TEST THE VALUE-GROWTH ASSUMPTION.
This calculator is deliberately a scenario tool, not a forecast. Change the purchase price, annual nominal value change and holding period. A good investment should still make sense if appreciation is modest.
Before transaction costs, tax, financing, maintenance, inflation and rental income. Not a forecast.
Development filters
WHAT WE WOULD CHECK BEFORE INVESTING
The right project should survive a conservative scenario. These filters are designed to separate genuine urban-growth exposure from marketing.
Planning status
Is the relevant sector plan approved, in public inquiry, or only conceptual?
Infrastructure timing
Is access already operational, funded and under construction, or only proposed?
End-user demand
Who will actually buy or rent the unit, at what monthly budget?
Competing supply
How many comparable units can be delivered in the same micro-market?
Entry price
Public investment cannot rescue an acquisition made materially above market value.
Exit liquidity
Would a local household, MRE buyer or investor have a reason to buy the unit later?
Investment conclusion
THE OPPORTUNITY IS THE INTERSECTION OF GROWTH, ACCESS AND HOUSING NEED.
Agadir has strong structural signals: sustained population growth, a highly urban population, smaller households, new sector plans, major public infrastructure and expanding employment zones. The investable opportunity is not “Agadir as a whole.” It is the specific residential locations where those forces overlap at a defensible purchase price.